An ambitious project can have a compelling market, a capable team and a credible route to capital. Yet one unexpected event can still interrupt delivery. A key person becomes unavailable. A site cannot operate. A supplier fails. A change in circumstances leaves the project unable to meet its commitments.
That is why protection deserves a place in project planning from the beginning. It is one part of a wider risk plan: understanding what could stop the project, deciding who would be affected and preparing a workable response.
It is easy to postpone this work. Early conversations tend to focus on what the project could achieve. The difficult questions about interruption, responsibility and recovery can feel premature. But those questions become harder and more expensive to resolve once funding discussions, contracts and delivery are underway.
Start with what the project depends on
Before considering any insurance product, map the dependencies that make the project viable:
- People: Which decisions or relationships depend on one founder, specialist or operator?
- Assets and locations: What premises, equipment, land or infrastructure are essential to delivery?
- Income and cash flow: What happens if work stops or revenue arrives later than expected?
- Contracts and partners: Who bears the cost when a supplier, contractor or partner cannot perform?
- Community and environment: What obligations arise from operating in a particular place or sector?
The answers will differ between an agricultural programme, a development project and an insurance platform. A useful protection plan starts with those differences, rather than a generic list of policies.
For example, a project that relies on one individual to secure land, maintain a critical relationship and approve spending has a concentration of responsibility. If that person steps away unexpectedly, the issue is larger than replacing a job title. The team needs to know who can make decisions, where the records sit and how commitments will be honoured.
The same exercise applies to physical operations. If access to a site is interrupted, what work can continue? Which costs keep running? What has been promised to partners? Asking these questions early makes the project plan more believable because it shows how the team intends to respond when conditions are less than ideal.
Make responsibilities clear
Risk planning is also a question of ownership. A project may involve founders, investors, lenders, operators and technical partners. Each needs to know which risks they control, which risks they carry and how an incident will be handled.
This should be reflected in the project's decision structure and contracts. Insurance may help transfer some financial risks, but it cannot replace sound governance, a realistic budget or a delivery plan. Some risks may be uninsurable or subject to exclusions, limits and conditions.
A useful conversation with partners might cover three questions: who notices and reports a problem, who has authority to act, and who pays for the immediate response. If those answers are unclear, even a relatively small setback can turn into a dispute or a long delay. Clear responsibilities help people move quickly and preserve trust.
Build protection into the financial model
A serious project budget should account for the cost of managing risk. That could include safety measures, contingency funds, specialist advice and suitable insurance where available. Leaving these questions until the final stage can change the funding requirement or delay delivery.
The aim is not to buy every possible form of cover. It is to understand the project's exposure, assess the available options and make deliberate decisions. Where regulated insurance advice is needed, a suitably authorised specialist should assess the circumstances and explain the terms.
The financial model should also test a plausible interruption. How long could the project meet its obligations if a milestone slipped? Which costs are fixed? Would a delay change the amount of capital required? A contingency allowance may answer some of these questions; other exposures call for operational controls, contractual changes or advice on possible insurance. The right combination depends on the project.
Revisit the plan as the project develops
The risk profile of an idea is different from that of a project acquiring land, hiring people or beginning operations. Review the protection plan at each major stage:
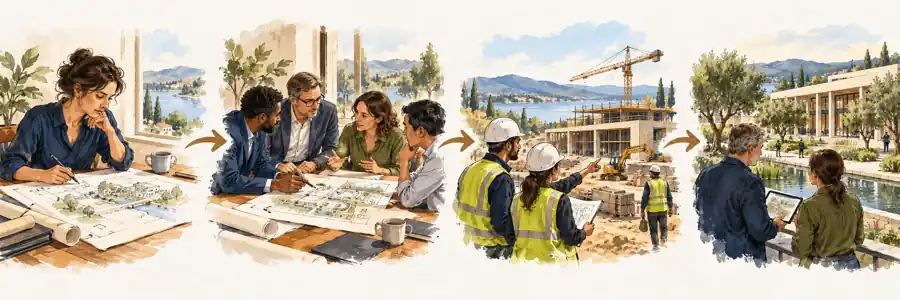
- Idea and feasibility: Identify the critical dependencies and potential losses.
- Capital and partner structuring: Agree who is responsible for each material risk.
- Before delivery: Confirm the controls, contracts, contingency and any relevant cover.
- During operation: Reassess when the team, assets, locations or commitments change.
Protection planning is ultimately about keeping a credible project capable of moving forward when circumstances change. It belongs alongside the business case, capital strategy, partner structure and delivery plan.
A simple starting exercise
Take one page and draw four columns: dependency, what could interrupt it, immediate response and owner. Fill it in with the project team. Start with the five dependencies that would cause the greatest delay or loss if they failed. This is not a complete risk assessment, but it will reveal where you need better information, clearer responsibilities or specialist advice.
Then ask whether the answers still make sense at the next project milestone. A plan made at the idea stage should evolve as facts replace assumptions and more people take on commitments.
A question for project founders: If one essential part of your project became unavailable tomorrow, what would happen next—and who would be responsible for the response?
This article is general information about project planning. It is not a recommendation for any insurance or investment product. The suitability and availability of cover depend on the project and its circumstances.